Has your financial aid package fallen short? You’re not alone.
Each year, students and parents complete the Free Application for Federal Student Aid (FAFSA), hoping their financial aid package will meet their full need. Sadly, more often than not, there is still a gap between what the student can afford with financial aid and what the school costs. And that’s with federal student loan options.
Below are steps that you can take to make college more affordable, from appealing your financial aid package and exploring institutional options, to comparing private student loan lenders and building a smart borrowing strategy.
Why Federal Student Loans Often Fall Short
Federal loans only cover a fraction of the cost of attendance at most colleges. You cannot borrow money to pay the full cost of attendance. Rather, there are annual and lifetime borrowing limits for federal student loans.
Federal Loan Limits by Year and Dependency Status
The Department of Education structures the annual and lifetime borrowing limits on subsidized and unsubsidized loans for undergraduate students as well as federal parent PLUS loans and graduate and professional student loans:
Federal Student Loan Limits 2026
| Student Status |
Year 1 |
Year 2 |
Year 3+ |
Lifetime Limits |
| Dependent |
Independent |
Graduate |
Professional |
Parent* |
| $5,500 |
$9,500 |
$20,500 |
$50,000 |
$20,000 |
| $6,500 |
$10,500 |
$20,500 |
$50,000 |
$20,000 |
| $7,500 |
$12,500 |
$20,500 |
$50,000 |
$20,000 |
| $31,000 |
$57,500 |
$100,000 |
$200,000 |
$65,000 |
*Amounts are per student.
Always borrow federal first and exhaust these loan options before turning to private student loans. For reference, students can only qualify for
subsidized student loans if they demonstrate financial need. They will be informed if – and for how much – they qualify for in their financial aid package.
At the same time, unsubsidized federal student loans are available to all students, regardless of whether they qualify for financial aid. You can take out both subsidized and unsubsidized student loans each year. To see full amounts for subsidized and unsubsidized loans, visit
studentaid.gov.
How the FAFSA Student Aid Index(SAI) Creates Gaps
The FAFSA provides a picture of a family’s financial circumstances so that schools can determine how much aid to disperse to a student. From the data collected, the Department of Education generates a Student Aid Index, or SAI, for each student, which reflects how financially needy they are.
Unfortunately, the system isn’t perfect. Sometimes, there are financial situations that are not depicted on the FAFSA. But most often, families feel more financially needy than the FAFSA algorithm implies.
When the Financial Aid Package Doesn't Reflect Real Need
The
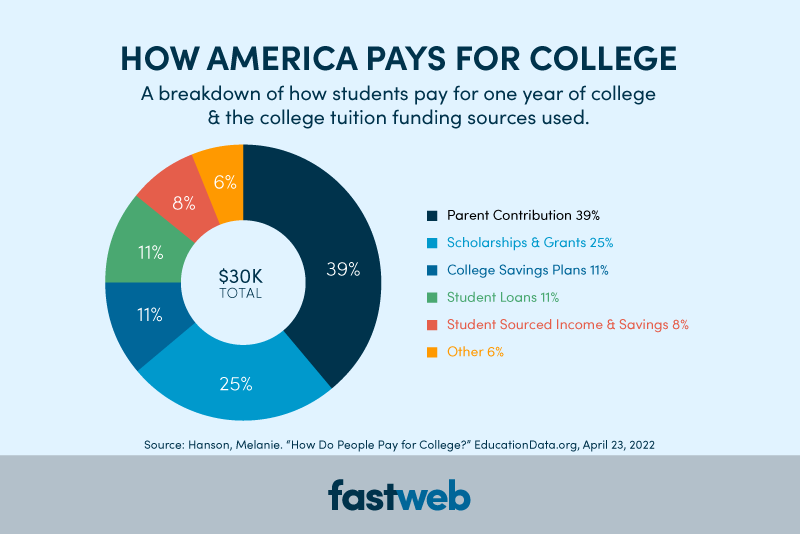
Education Data Initiative reports that the average cost of attendance for college is $38,270 per student per year. This figure includes tuition, fees, room and board, books, supplies, and living expenses.
The
EDI also reports that students and families pay 48%, or an average of $13,760, of out-of-pocket college costs. Yet,
Saving for College reports that the average amount of financial aid received is $16,810 – and that includes federal student loans.
Essentially, for most American families, there exists a gap between what they’ve saved, what they’ve qualified for in financial aid, and what they still owe. So, what can they do next?
Step 1: Appeal Your Financial Aid Package Before Borrowing More
Did you know that you can appeal your financial aid package? If you believe you deserve more financial aid, find out what you can do to earn it.
What Qualifies as Grounds for a Financial Aid Appeal
Because the FAFSA asks for the prior-prior year financials for the families, there may be circumstances that make a family more needy than they appear and qualifies them for a
financial aid appeal. This includes:
• Job loss or pay cut
• Business closure
• Loss of benefits
• Divorce or separation
• Death of a parent or spouse
• Dependency override (for students who are technically dependent but should be considered independent for financial aid purposes)
• Large medical bills
• Special needs or senior care
• Property loss
Circumstances and appeals processes vary by student and institution. If you think you may be eligible for an appeal, reach out to a financial aid administrator as soon as possible.
How to Write a Financial Aid Appeal Letter
A financial aid administrator will ask that you send a financial aid appeal letter (this could be a hard or electronic copy). Additionally, they will ask for documentation to establish your claim. Asking for an appeal can be daunting; that’s why we’ve provided a
financial aid appeal letter template.
The appeals process can vary, but it could take up to a month to hear from the school. In the meantime, you should exhaust other options to help you pay for school.
Step 2 — Exhaust All "Free Money" Options First
If your financial aid package has come up short, be sure you’re exploring all options to help you pay for school. With the high price tag of college, many families have to get creative in how to pay for college:
Students and parents can explore the following:
•
Update the Fastweb profile to see which scholarships for college students you may have missed and commit to applying to 1-2 per week. Scholarship winners consistently say that they apply to hundreds – if not thousands – of scholarships before they win one.
•
Submit your FAFSA by the state deadline to qualify for state grants and aid – not just federal aid.
• Secure a part-time job with an employer who will pay college costs through their
tuition reimbursement program.
•
Find a work-study job on campus that allows you to balance your student schedule and send your paychecks straight to the registrar’s office to cover your tuition bill.
Step 3 — How Private Student Loans Work (and When to Use Them)
Once you’ve exhausted the above options, it’s time to turn to private student loans.
What is a Private Student Loan?
In the education world, colleges often refer to loans made directly by banks and other lending organizations as "private" or "alternative" loans to distinguish them from federal loans. Private loans can be used alone or in conjunction with federal loans.
Federal Loans vs Private Loans: Key Differences at a Glance
The primary difference between federal loans and private loans is that the government guarantees federal loans against default. If a borrower defaults on repaying a federal loan, the government repays a portion of it.
Many lenders provide funds for both federal and private education loans. Because there is less risk to a lender with a federal education loan, interest rates are generally lower for those loans than for private loans, for which a
private student loan lender assumes all risk that the loan will be repaid.
Below are key differences:
| Federal Loans |
Private Loans |
| Financial aid forms required |
Financial aid forms not required by private student loan lender |
| Loan limits determined by year in school |
Higher loan limits |
| Schools must authorize the loan amount |
Signer and co-signer must have good credit |
| Funds are sent to the school |
Funds may be sent to borrower |
| Satisfactory Academic Progress required to receive additional loans |
Faster application process |
| Repayment Assistance Plan available |
Repayment options |
| 10-, 15-, 20-, and 25-year standard repayment plan available |
Longer repayment loan terms and variable rates |
| Restrictions on how loans may be used |
Fewer restrictions on how the loan may be used (as for a computer for college or transportation) |
The Role of a Cosigner and How It Affects Your Rate
One of the greatest differences between federal and private loans is the need for a cosigner for private student loans. Typically, a cosigner is required because the student does not have a credit history or consistent income to allow for borrowing.
If the student borrower consistently makes payments after graduation, cosigning on a private loan will not hurt the cosigner. Additionally, many private lenders have a cosigner release written into the document, which allows for the cosigner to be released from the loan after the borrower makes 24 – 48 consistent payments.
How Much Can You Borrow with a Private Student Loan?
Another major difference between federal and private loans is the amount students can borrow. Most private student lenders will allow you to
borrow up to the full cost of attendance, minus any merit and financial aid you receive. They may also come with larger lifetime borrowing limits.
Smart Borrowing Rules to Protect Your Future
Sometimes, private student loans can be the easy way out. It takes less time to apply for a private student loan than it does for scholarships. However, it’s important to keep in mind these smart borrowing strategies to minimize
student loan debt.
The "1x Salary Rule" Explained
One of the best rules of thumb for borrowing is to never borrow more than your expected annual salary after graduation. This takes a bit of research. Find average starting salaries for your major or field of interest using a salary finder, like
Salary.com or
Glassdoor.
This number should be the total amount borrowed over the course of your college career – not per year. For example, if your annual salary is estimated to be $50,000, do not borrow more than that number for all four years of college, or however long it takes to complete your undergraduate degree.
Avoiding Over-Borrowing: What to Consider Before Signing
As you plan to borrow to pay for college, consider the entire cost of the loan. This includes the principal balance, loan interest that will accrue over time, and rates and fees.
Calculators from FinAid can help you estimate the total cost of your private student loan.

 Students and parents can explore the following:
• Update the Fastweb profile to see which scholarships for college students you may have missed and commit to applying to 1-2 per week. Scholarship winners consistently say that they apply to hundreds – if not thousands – of scholarships before they win one.
• Submit your FAFSA by the state deadline to qualify for state grants and aid – not just federal aid.
• Secure a part-time job with an employer who will pay college costs through their tuition reimbursement program.
• Find a work-study job on campus that allows you to balance your student schedule and send your paychecks straight to the registrar’s office to cover your tuition bill.